The capital gains tax (CGT) reforms have sparked debate about whether investors should favour income-producing investments over those focused on growth, in an effort to reduce their tax bill.
But a lower tax bill doesn’t necessarily lead to a better investment outcome.

New modelling of the reforms suggests that while higher-growth investments could face larger tax liabilities under the new rules, they may still leave investors with greater after-tax wealth over the long term.

Understanding the changes

Under the current rules, Australian investors who hold an asset for more than 12 months may be eligible for a 50% discount on capital gains.

From July 1, 2027, that approach will be replaced with an indexed cost-base methodology, designed to account for inflation when calculating taxable gains1. The proposal would also introduce a minimum tax rate of 30% on capital gains.

To understand how these changes could affect investors, here is a model of two hypothetical portfolios over a 20-year period.2

  • A higher-income portfolio generating 6% annual income and 4% annual capital growth.

  • A higher-growth portfolio generating 2% annual income and 8% annual capital growth.

Both portfolios were assumed to deliver the same total pre-tax return of 10% per year. The key difference is how those returns are generated. 

Different returns, different tax outcomes

The reforms produce very different tax outcomes for the two portfolios. Under the new rules, the higher-income portfolio is around $4,000 better off than under the current regime, while the higher-growth portfolio is about $29,000 worse off.


Portfolio

Current rules after-tax value

New rules after-tax value

Difference

Higher income
(6% income, 4% growth)

$180,448

$184,427

+$3,979

Higher growth
(2% income, 8% growth)

$234,906

$205,719

-$29,187

Note: The example is illustrative only and is based on the factors stated. It should not be taken to contain or provide an estimate, projection or guarantee of future investment returns or tax outcomes. 

The difference largely comes down to the relationship between capital growth and inflation. Investments with relatively strong capital growth generally benefit more from today’s 50% CGT discount, while lower-growth investments may benefit more from an indexation approach. Keep in mind a portfolio with greater exposure to growth assets would generally be expected to experience greater fluctuations and a higher risk of loss than a lower-growth portfolio.

However, tax is only part of the story. Despite facing a larger CGT bill under the new rules, the higher-growth portfolio still finishes with more after-tax wealth after 20 years, accumulating approximately $205,700 compared with $184,400 for the higher-income portfolio.

This is because a greater proportion of the higher-growth portfolio’s return remains invested and compounds over time. This highlights an important distinction: the investment that generates the lowest tax bill may not be the one that leaves you with the most money after tax. In some cases, paying more tax may simply be a by-product of generating higher returns. 

What about different markets?

This distinction may also be relevant when comparing different markets. Australian shares have historically delivered a larger portion of returns through income, while international shares have tended to generate more of their returns through capital growth. Under the reforms, those differences could lead to different tax outcomes, but investors should remain focused on total after-tax returns rather than tax outcomes alone. 

The bottom line

The CGT reforms could change the relative tax treatment of income and capital growth. While this modelling suggests lower-growth portfolios may benefit from an indexed cost base and higher-growth portfolios could face larger CGT liabilities, tax is only one part of the equation.

The modelling shows that even after paying more CGT, a higher-growth portfolio can still generate greater after-tax wealth over the long term because more of its return remains invested and compounds over time. However a higher growth portfolio would also increase the exposure to market fluctuations and a higher risk of loss.

The right portfolio will depend on an investor’s goals, risk tolerance and circumstances. Tax outcomes are not guaranteed and will vary between investors. Rather than focusing solely on minimising tax, investors should focus on maximising long-term after-tax wealth.


1. Note that if you had acquired assets prior to 1 July 2027, part of your capital gain may be subject to the CGT discount if it was held for at least 12 months; however this discount gain is deferred until you sell your asset.

2. The modelling assumes an Australian resident individual investor eligible for the CGT discount under the current rules and a $50,000 initial investment, a 20-year holding period, a marginal tax rate of 47%, annual inflation of 2.7%, reinvestment of after-tax income distributions reinvested annually, and payment of CGT at the end of the investment period. Investment fees, transactions costs and Medicare levy are not included.

Important Information
This article contains certain ‘forward looking’ statements. Forward-looking statements, opinions and estimates provided in this article are based on assumptions and contingencies which are subject to change without notice, as are statements about market and industry trends, which are based on interpretations of current market conditions. Forward-looking statements including projections, indications or guidance on future earnings or financial position and estimates are provided as a general guide only and should not be relied upon as an indication or guarantee of future performance. There can be no assurance that actual outcomes will not differ materially from these statements. To the full extent permitted by law, Vanguard Investments Australia Ltd (ABN 72 072 881 086 AFSL 227263) and its directors, officers, employees, advisers, agents and intermediaries disclaim any obligation or undertaking to release any updates or revisions to the information to reflect any change in expectations or assumptions. This article is not a substitute for tax advice; it has been prepared on a set of assumptions which may not be applicable to you. If you are in any doubt about your personal tax position, we recommend that you seek advice from a registered tax agent or a suitably qualified adviser.

Source: Vanguard
Reproduced with permission of Vanguard Investments Australia Ltd
Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance.
© 2026 Vanguard Investments Australia Ltd. All rights reserved.
Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.
Teaching kids about money

Raising your kids to be smart with money gives them vital life skills.

Helping younger kids understand money

As a parent, you can shape your child’s relationship with money from an early age.


You don’t need to be a money expert to teach kids about money. Simple conversations at home and everyday moments can help kids understand where money comes from, where it goes, and how to use it wisely.

Money conversations change as kids grow. What works for a young child will be different to what works for a teenager. But regular conversations can help build confidence and financial literacy over time.

How you earn money

Talk about how you earn the money you spend. 

Explain that you get paid for the work you do. Then show your child how you use that money to pay for things your family needs, such as food, clothes, transport and housing.

As kids get older, you can also talk about banks, savings accounts and digital payments.

What’s the difference between needs and wants?

Talk about how you decide what to spend money on. 

Needs are things we need for everyday life, such as food, housing and clothing. Wants are things we would like to have but can live without.

When your child asks for something, talk about whether it is a need or a want. This helps kids think about spending choices before they buy.

Show your kids where money goes

There are plenty of everyday opportunities to teach your kids about money.

When you tap and pay

Kids often see people pay with cards, phones and smart watches.

Explain that tapping to pay still uses real money from a bank account. Each purchase leaves less money to spend or save.

While shopping

Shopping can help kids learn about price, value and choice.

You can:

  • compare prices on similar products

  • point out discounts and special offers

  • look for the unit price (for example, price per 100g) 

  • compare which item offers better value

  • talk about whether something is a need or want.

When paying bills

Show your child a household bill, such as an electricity, internet or mobile phone bill. 

Talk about what the bill covers and how you use your income to pay for it. This helps kids connect earning money with paying for everyday things.

Looking for ways to practise at home? You can use Moneysmart’s primary school lessons and activities with your kids at home. They cover topics like needs and wants, budgeting, saving and making spending decisions. Explore primary school lesson plans.

Help kids learn by doing

As kids get older, they learn more when they start making their own money decisions.

Giving kids some responsibility for money can help them build confidence and learn from small choices while the stakes are low.

Should kids get pocket money?

There is no right or wrong approach.

Some parents give pocket money each week. Others link it to certain jobs around the house, such as:

  • mowing the lawn

  • vacuuming the house

  • making school lunches

  • hanging out and bringing in the washing

  • packing and unpacking the dishwasher

  • washing the car

  • taking out the rubbish

  • walking the dog.

Do whatever works for your family and circumstances.

Having their own money can help kids practise spending, saving and making choices.

Encourage your kids to save

Learning to save is an important life skill.

Piggy banks work well for younger kids because they can watch their money grow. 

As kids get older, a savings account can help them learn about banking, saving and interest, including the power of compound interest.

There are also apps to help kids save money and develop good money habits.

How can kids save for a goal?

Help your child save for something they really want.

When they want to make an impulse buy, talk about the goal they’re saving for and how today’s spending might affect it. 

You can use a savings goal calculator to help them see how different choices affect their progress.

Plan an event together

Invite your child to help plan a birthday party, family outing or special activity. 

Work through the costs together and talk about what fits the budget. This helps kids practise planning, prioritising and making spending decisions.

Do a budget together

Talk through parts of the family budget with your kids. 

Show them how much money comes in and how you use it for things like food, bills, transport and savings. This can help them understand the cost of living and how planning ahead helps. 

If they are earning money, show them how to create their own budget using this budget planner.

Help your kids learn with the budget planner

Track their spending

When older kids start earning or receiving money regularly, they may feel tempted to spend it all at once.

Show them how to track their spending so they can see where their money goes. This can help them make more informed choices about spending and saving.

Share their money

Some families include giving as part of learning about money.

If your child wants to support a charity or cause they care about, talk about how donations can help others and how giving fits alongside spending and saving.

Help teens build money skills for adulthood

Money conversations don’t stop when kids become teenagers.

As young people gain more independence, parents can still play an important role. You can help them build confidence, understand risks and prepare for bigger money decisions.

What should teenagers know before their first job?

Getting a first job is an exciting milestone.

It’s also a good time to talk about:

For many teenagers, this is the first time they earn and manage their own money.

How can I help my teenager manage money?

Teenagers often start saving for bigger goals, such as a concert, a holiday, study costs, a car or moving out of home.

Help them set a savings goal, create a simple budget and track their spending. These money skills can help them make confident financial decisions later in life.

They can also use the budget planner or savings goals calculator to make a plan.

Saving for a car

Many teenagers save for a car as one of their first big money goals.

Talk about the full cost, not just the purchase price. This may include registration, insurance, fuel, servicing, repairs and loan repayments.

Comparing options and planning ahead can help them make a more informed decision.

How can I help my teenager avoid money mistakes?

Encourage your teenager to ask questions before signing up for new products or services. A quick conversation can help them understand the costs, risks and alternatives before they commit.

Teenagers and young adults often make more money decisions online.

Talk about things like:

These conversations help young people recognise risks and make informed decisions.

Keep the conversation going

As your teenager gets older, they’ll start making bigger money decisions. 

They might start asking questions about managing money while studying, buying a car, moving out of home, rental bonds and leases, or saving for a home.

You don’t need to have all the answers. But your guidance still matters.

Talking through options together can help them build confidence and make informed choices.

Source: Moneysmart
Reproduced with the permission of ASIC’s MoneySmart Team. This article was originally published at https://moneysmart.gov.au/family-and-relationships/teaching-kids-about-money
Important note: This provides general information and hasn’t taken your circumstances into account.  It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person.  Past performance is not a reliable guide to future returns.
Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.
What is your ‘estate’?

Your ‘estate’ includes everything you own – your ‘earthly possessions’, if you will. It can include for example cash, property, cars, boats, furniture, jewellery, family heirlooms, art, shares and more.

What is estate planning?

This is where you decide what will happen to your belongings after you pass away. By leaving a clear set of ‘instructions’, you help make sure that the people you care most about aren’t faced with any unnecessary conflict or uncertainty.

Why is estate planning important?

Even if you don’t have much money or property, planning your estate is the best way to make sure that special belongings go to the people who will treasure them. Often, it’s these items that matter most.

Why an estate plan is a good plan

  • Your assets get passed on to beneficiaries that you choose. If you pass away without a valid will (and in turn, without a valid estate plan) you’re considered to have ‘died intestate’ and your assets get distributed according to your state’s inheritance laws—not your wishes.
  • If you leave kids behind, you decide who cares for them and how—not the courts.
  • You minimise the tax your beneficiaries may pay when they inherit your assets.
  • You reduce the risk of conflict between family and friends when you pass away.

What’s in your will?

Your will is a legal document that’s part of your estate plan. It outlines how you want your estate to be managed and how you want your assets to be distributed when you pass away.

If you have a fairly straightforward estate and know how you’d like to distribute it, you can easily write your will yourself. It’s as simple as buying a will pack from Australia Post and select news agencies, or downloading it online.

For more complicated estates, it might be a good idea to get advice from a solicitor or the Public Trustee. You can then appoint them to be your executor.

Your will checklist

Your will should:

  • clearly identify your beneficiaries
  • clearly identify your executor
  • have the right date on it
  • be signed correctly
  • be witnessed correctly
  • list exactly how you want your estate to be distributed to your beneficiaries (including any plans if they pass away before you)
  • be up to date.

Should you review your estate plan?

Life is never predictable, so it’s a good idea to update your estate plan when things change.

Why you might change your estate plan

  • You get married.
  • You get divorced.
  • You have kids.
  • Your partner, dependant or loved one passes away.
  • You experience financial hardship.

Other things to consider

Organising life insurance and a funeral plan can make things easier for your family later. Learn the ins and outs of life insurance, or find out about estate planning in more detail with ASIC’s Moneysmart guide.

Source: NAB
Reproduced with permission of National Australia Bank (‘NAB’). This article was originally published at https://www.nab.com.au/personal/life-moments/family/will
National Australia Bank Limited. ABN 12 004 044 937 AFSL and Australian Credit Licence 230686. The information contained in this article is intended to be of a general nature only. Any advice contained in this article has been prepared without taking into account your objectives, financial situation or needs. Before acting on any advice on this website, NAB recommends that you consider whether it is appropriate for your circumstances.
© 2026 National Australia Bank Limited (“NAB”). All rights reserved.
Important:
Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.
How well do we understand our money?

Most of us make financial decisions almost every day.

We decide whether to save or spend, how much of the mortgage to pay down, where to invest and, eventually, how to turn decades of savings into an income that can support us through retirement.

But how well do Australians understand the financial concepts and systems behind those decisions?

Vanguard’s How Australia Retires 2026 report surveyed more than 1,800 Australians and found that while older Australians showed higher financial knowledge than younger Australians, significant gaps remain across everything from basic investment concepts to superannuation and the retirement system.

And that’s important because financial literacy isn’t about becoming an investment expert. It’s about having enough knowledge to make informed decisions about your money throughout your life.

How would you fare on the ‘Big Three’ questions?

To measure financial literacy, we asked Australians three internationally recognised questions developed by researchers Annamaria Lusardi (Stanford University) and Olivia Mitchell (University of Pennsylvania), which have been used to assess financial knowledge around the world.

They’re designed to test three foundational financial concepts: interest, inflation and diversification.

Have a go at the following and see how you do:

  1. Suppose you put $100 into a zero-fee savings account paying a guaranteed 2% interest rate. You make no further deposits or withdrawals. How much would you have after one year?

  2. Imagine the interest rate on your savings account was 1% a year while inflation was 2%. After one year, would your money allow you to buy more than today, exactly the same amount, or less?

  3. True or false: Buying shares in a single company usually provides a safer return than buying shares in a number of different companies.

We’ll reveal the answers at the end of this article, but first, how did Australians fare in the How Australia Retires 2026 report?

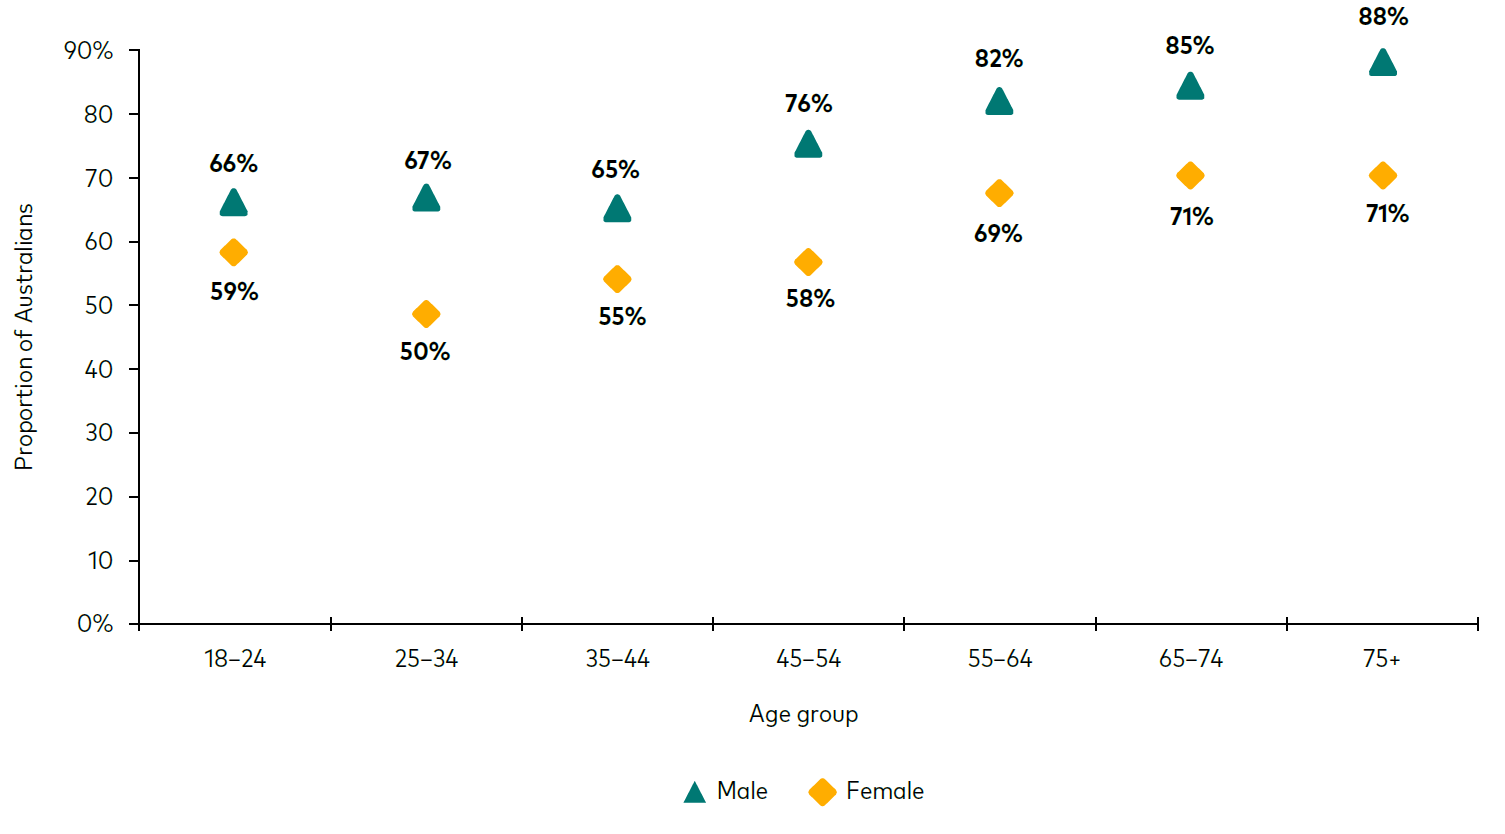
  • Financial literacy scores were generally higher among older Australians. Scores were relatively consistent among Australians aged 18-44 before rising substantially among older age groups. Men aged 55+ recorded average scores above 80%, with men aged 75+ achieving the highest score of 88%.

  • Younger Australians are improving. Men aged 18–24 scored 66%, up from 54% last year, while women in the same age group scored 59%, up from 50%.

  • The gender gap persists. Women scored below men across every age group, with the largest gap among 45–54-year-olds: 76% for men versus 58% for women.

 Financial literacy by age and gender

Source: Vanguard’s How Australia Retires Report 2026 (page 10).

Retirement knowledge remains a challenge

Understanding concepts such as inflation and diversification is one thing.

Navigating Australia’s retirement system is another.

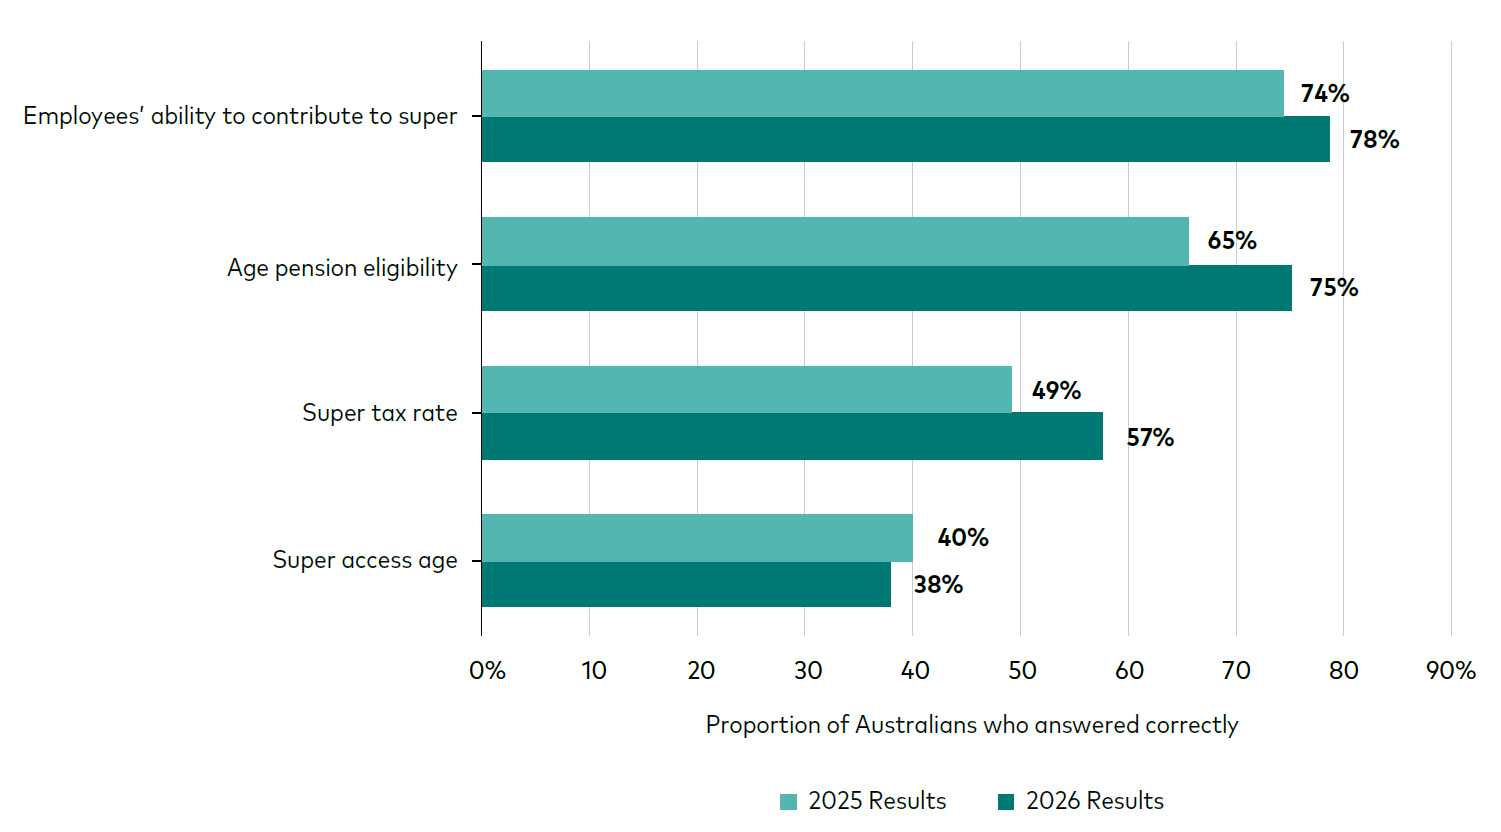
Respondents were asked four questions covering the Age Pension, voluntary super contributions, the taxation of super and when people can generally access their super savings.

The results were mixed.

  • Knowledge of voluntary super contributions improved. 78% correctly understood that employees can contribute to their own super, up from 74% last year.

  • More Australians understand Age Pension eligibility. 75% answered correctly, up from 65%.

  • Understanding of super’s tax treatment also increased. 57% answered correctly, compared with 49% last year.

  • Super access remains a major blind spot. Just 38% correctly identified the super preservation age, down from 40% last year. Among women aged 18–34, fewer than 30% answered correctly.

That’s a significant knowledge gap given super is likely to become one of the largest financial assets many Australians own.

Australians’ understanding of the retirement system

Source: Vanguard’s How Australia Retires Report 2026 (page 12).

How well do Australians understand their super?

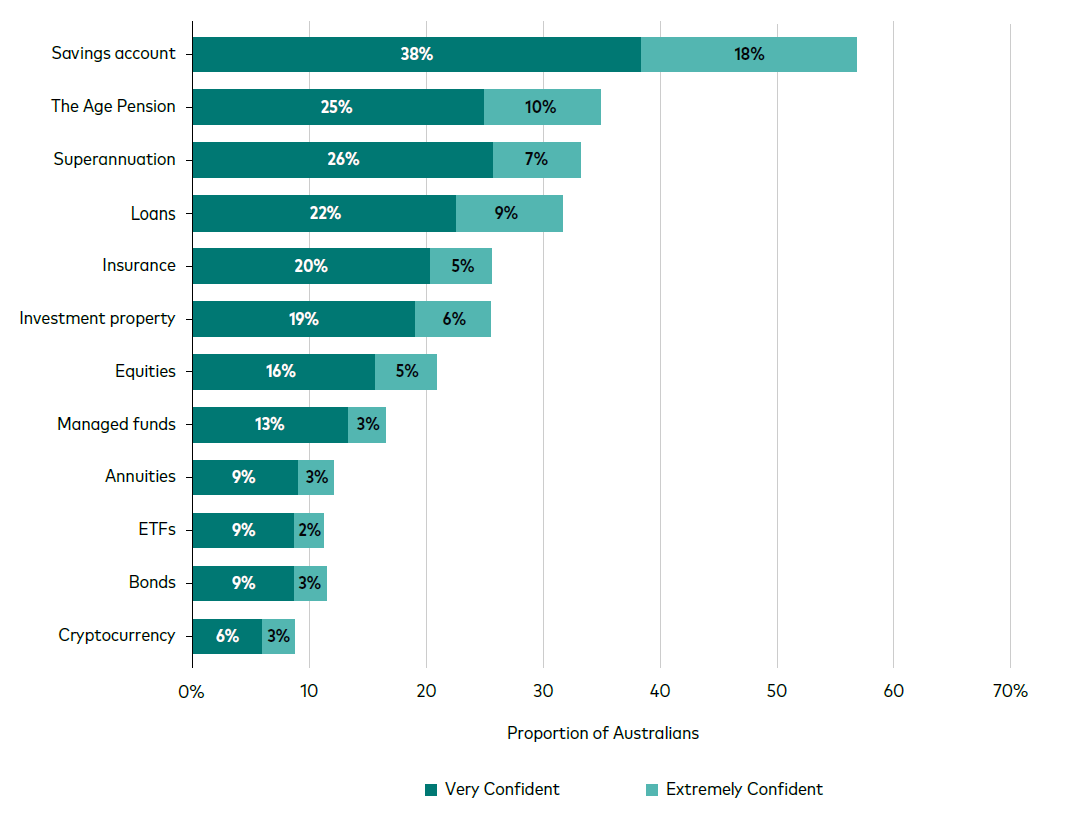
The research also asked the 1800 Australians surveyed how confident they felt about understanding different financial products.

Unsurprisingly, the humble savings account came out on top: 56% reported being very or extremely confident in their understanding.

But confidence dropped considerably for products that can play an important role in building and funding retirement.

Only around one-third of Australians reported high confidence in understanding superannuation, while confidence was even lower for equities, managed funds, ETFs, bonds and annuities.

More broadly, just 35% of Australians said they were very or extremely confident in making financial decisions, slightly below 37% last year.

Australians’ confidence managing financial products and services

Source: Vanguard’s How Australia Retires Report 2026 (page 13)

Fees are another area where knowledge could improve.

Nearly half of Australians said they wouldn’t feel confident explaining the fees charged on their super account to a friend or family member, while more than one-third weren’t very aware – or weren’t aware at all – that super funds may charge multiple fees.

Over long investment periods, even small differences in fees may have a significant impact on your investment balance. The extent of that impact will depend on factors such as investment returns, fees and your individual circumstances.

Vanguard’s modelling found that an additional 0.5 percentage points in annual fees could reduce the retirement balance of a hypothetical full-time worker by around $77,000, or approximately 12.5% of their accumulated savings under the assumptions used in the analysis.1

Building your financial knowledge

The good news is that financial literacy isn’t something you either have or don’t have.

It’s something that can be built gradually through reading, research, conversations and experience.

You could start with some of the fundamentals: understand how inflation affects your purchasing power, learn how compound returns work, explore the relationship between investment risk and return, and understand why diversification matters.

When it comes to retirement, make a habit of learning how your super works, how your savings are invested, what fees you’re paying and how the Age Pension fits into Australia’s broader retirement system.

Make a start

Australians are encouraged to take small, practical steps towards their financial future, whether it’s logging into your super account, learning something new about retirement or beginning to map out a plan. Now is a good time to take your first or next step in your retirement planning journey.

Access How Australia Retires 2026

1 Compares two hypothetical MySuper scenarios for a 25-year-old member with a starting balance of $24,004 and salary of $83,200, retiring at 67. Assumes 12% p.a. SG contributions (less 15% tax), 6.4% p.a. nominal returns, $173 p.a. life and TPD premiums and annual fees of 0.56% and 1.06%. Salary and premiums increase by 4.0% p.a. inflation (2.5% CPI plus 1.5% rising community living standards). End balances are shown in today’s dollars. This example is for illustrative purposes only.
Answers to financial literacy questions:
1. Exactly $102.
2. Less than today.
3. False.
Important information:
Source: Vanguard How Australia Retires 2026 research. Nationally representative survey of 1,800+ Australian adults aged 18 years and over in February 2026. The full methodology is available on page 62 of the report.
Note: Survey findings and examples are based on Vanguard’s How Australia Retires 2026 research and reflect respondents’ opinions, expectations and intentions at the time of the survey. They should not be taken as forecasts or predictions of individual retirement outcomes.
Source: Vanguard
Reproduced with permission of Vanguard Investments Australia Ltd Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance. © 2026 Vanguard Investments Australia Ltd. All rights reserved. Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.
A very different retirement awaits

For generations of Australians, owning the family home outright by retirement was almost taken for granted.

You bought a house during your working years, gradually paid down the mortgage and ideally entered retirement debt-free, with superannuation and the Age Pension available to help fund your lifestyle (or, if you were fortunate, an employer-sponsored defined benefit pension).

For many younger Australians, that same path is becoming increasingly difficult.

Research reveals a generation expecting to work longer, carry substantially more housing debt into retirement and need considerably more income once they get there.

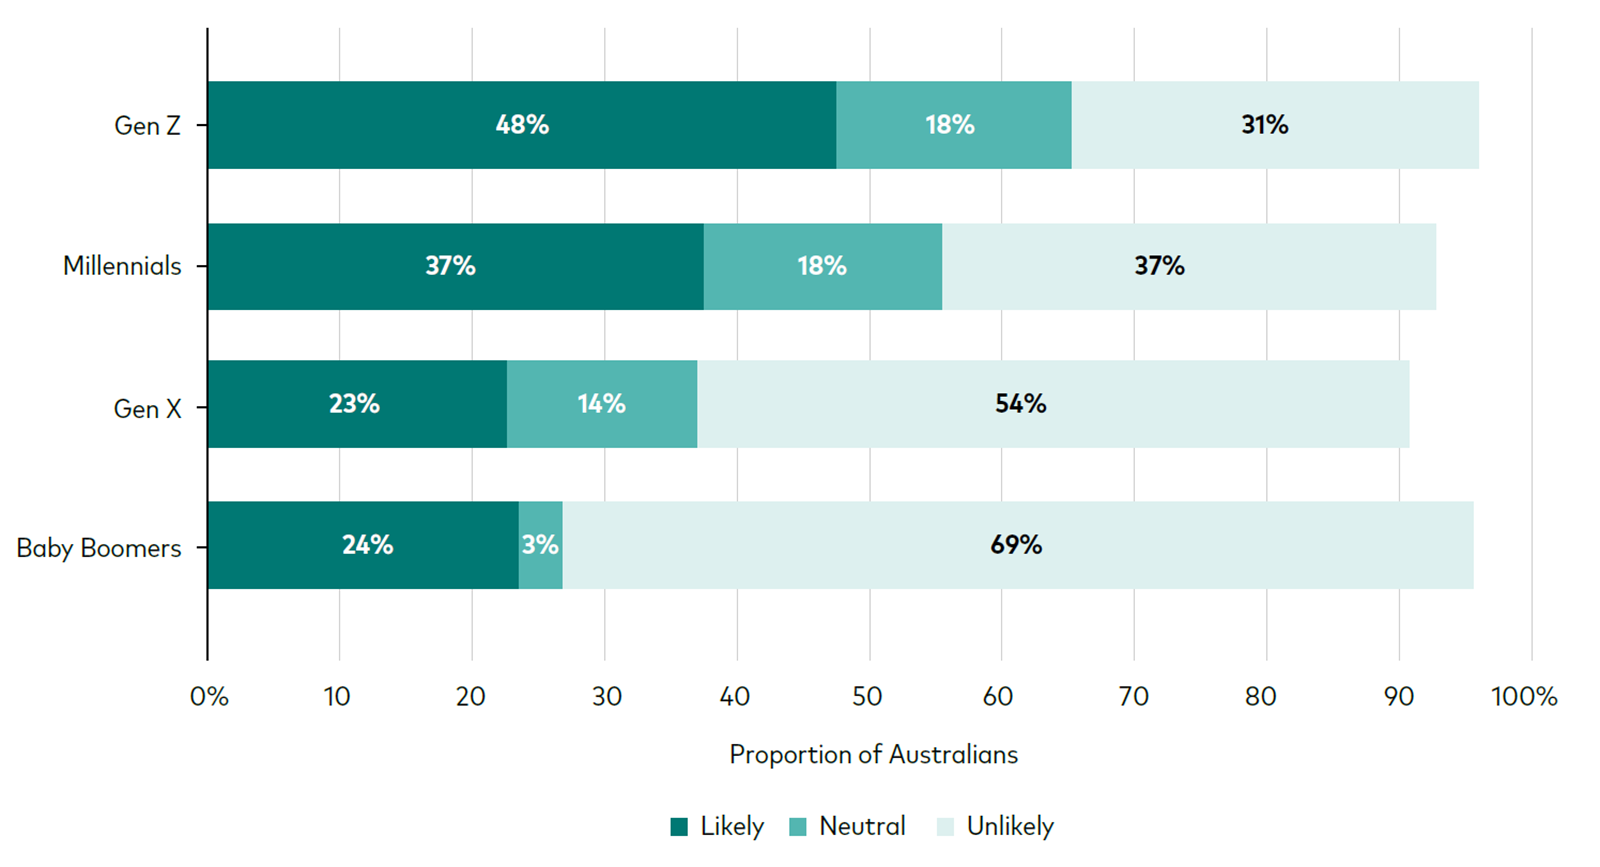
Nearly half of Gen Z Australians (48%) surveyed expect to still have a mortgage in retirement, alongside more than one in three Millennials (37%) surveyed, while others expect to remain renters throughout retirement.

Self-assessed likelihood of retiring with a mortgage

Source: Vanguard’s How Australia Retires 2026 survey of more than 1,800 Australians. Results are based on survey responses and are intended for illustrative and informational purposes only.

Using super to pay off the mortgage

These shifts could fundamentally change how younger cohorts eventually fund their retirement. Of those expecting to retire with a mortgage:

  • 39% are considering using some of their super to pay off their debt

  • 16% expect to sell their property

  • 45% plan to continue making mortgage repayments during retirement.

Daniel Shrimski, Vanguard’s Managing Director, Asia Pacific, says the findings demonstrate how much the path to retirement is changing.

“Australians are facing a tougher road to retirement than previous generations. Higher housing costs, bigger debts and cost-of-living pressures are changing what retirement looks like and what it will take to fund it,” he said.

Whether using superannuation savings to repay debt is appropriate will depend on individual circumstances and may impact retirement income. Individuals should consider seeking professional advice.

Younger Australians expect to retire later

Housing isn’t the only thing changing.

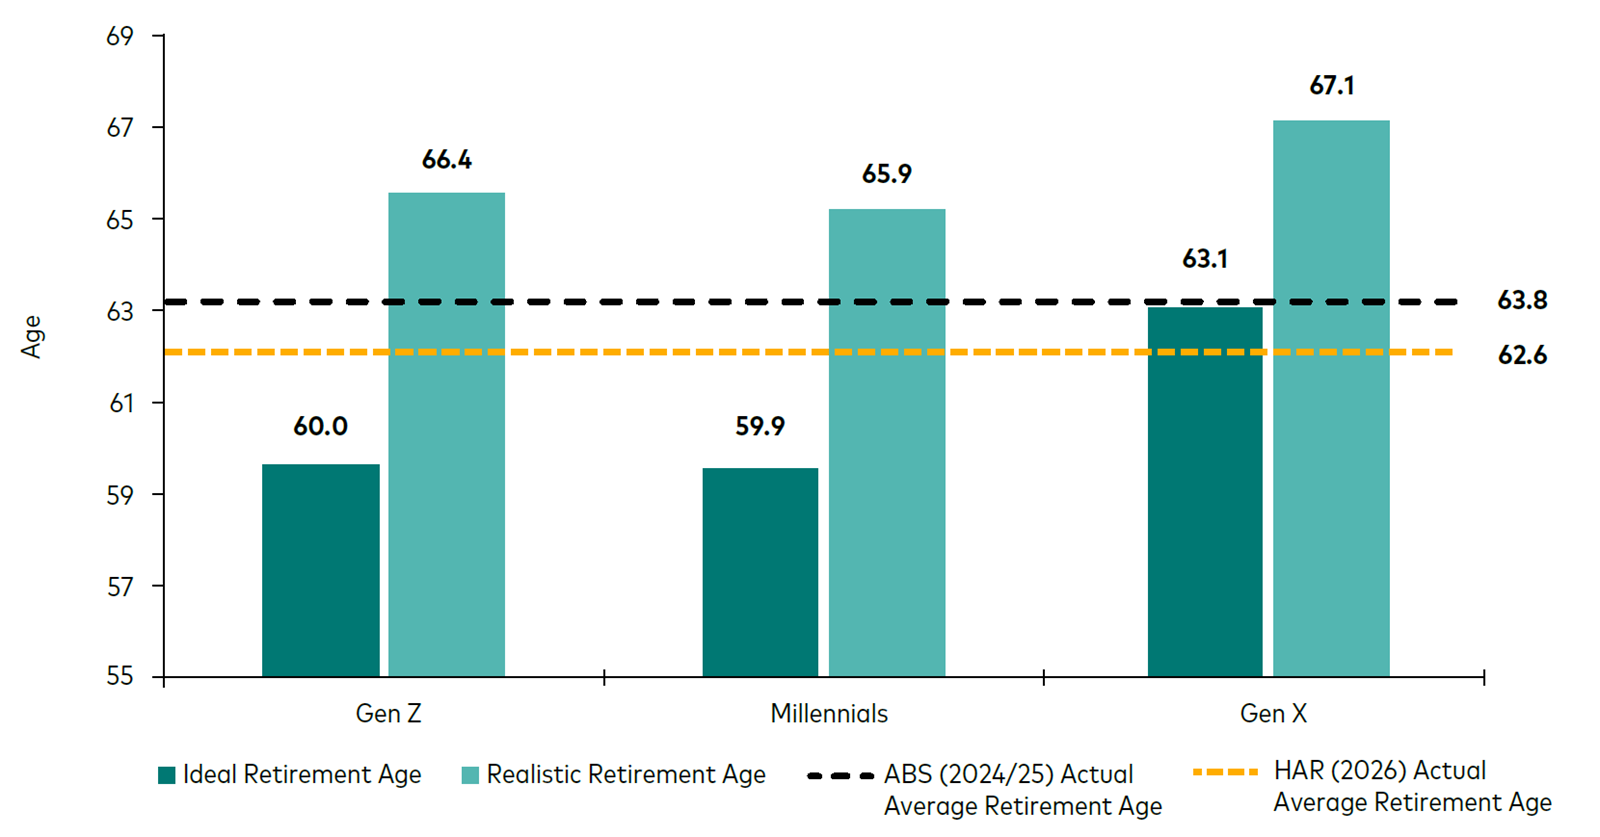
The research, based on a nationally representative survey of more than 1,800 Australian adults, found most working-age Australians now expect to retire at age 66 or 67.

By comparison, Australians who are already retired reported leaving the workforce at an average age of 63. 

Working-age Australians’ estimates of their ideal and realistic ages at retirement

Source: Vanguard’s How Australia Retires Report 2026 (page 28).

Working an additional three or four years can have significant financial implications. It provides additional years of employment income and super contributions while delaying the point at which someone needs to begin relying on their retirement savings.

But for some Australians, working longer may increasingly be a necessity rather than a choice.

The research suggests housing security is emerging as an important factor in retirement confidence, with younger generations facing the prospect of simultaneously funding their retirement lifestyle and continuing to meet housing costs.

The $90,000 retirement

Despite these pressures, Australians continue to have high expectations for life after work.

The research found Australians aspire to an active retirement that includes remaining in their own home, travelling regularly and spending money on hobbies and their health.

But younger Australians believe funding that lifestyle will require substantially more money.

Australians under 45 estimate they will need over $90,000 a year in retirement. By comparison, Australians aged 65 and over report needing around $60,000 a year.1

Some of that difference may reflect the longer time younger Australians have before retirement and expectations that inflation will push up the cost of living.

But it also illustrates the challenge ahead: younger Australians expect retirement to cost more while simultaneously anticipating entering it with greater housing expenses.

Planning remains a major gap

While retirement expectations are changing, one of the biggest opportunities identified by the research is surprisingly simple: having a plan.

Despite compulsory superannuation, many Australians still don’t have a retirement plan.

“While 45% of working-age Australians have no retirement plan, our research shows that people who have started planning for retirement are significantly more confident about their future,” Shrimski says.

The chart below shows how retirement confidence varies depending on the level of planning.

Retirement confidence by level of retirement planning

Source: Vanguard’s How Australia Retires Report 2026 (page 23).

It doesn’t need to be complicated

A retirement plan doesn’t necessarily need to be complicated. It can start with a few basic questions, whether you’re thinking them through yourself or discussing them with your partner, family or friends:

  • When would you like to retire?

  • Where would you like to live?

  • What sort of lifestyle do you want?

  • How much super do you currently have?

  • Will you still have a mortgage?

  • How much income might you need?

Answering those questions may help identify the gap between where you are today and where you would like to be.

Small steps can make a difference

The good news is that retirement planning doesn’t need to happen all at once.

The research highlights several practical actions Australians can take to become more engaged with their financial future:

  1. Build a retirement plan. Think about your future goals and the steps that could help you achieve them.

  2. Understand how the retirement system works. Learn about superannuation and the role it can play alongside the Age Pension.

  3. Improve your financial literacy. Build your understanding of basic financial concepts through reading, research and conversations.

  4. Consider additional super contributions. Where your circumstances allow, extra contributions may help strengthen your retirement savings.

  5. Check your super regularly. Aim to review your balance, contributions and investment options at least every six months.

As Shrimski puts it: “Our research shows that small actions taken consistently over time can build confidence and help Australians prepare for the retirement they want.”

For younger Australians facing higher housing costs, larger mortgages and potentially longer working lives, the retirement journey may look very different to the generations before them.

But the basic principle remains the same: the earlier you understand where you stand and where you want to go, the more options you may have to shape the retirement you ultimately experience.

1. How Australia Retires 2026, (page 31).
Important information:

Source: Vanguard How Australia Retires 2026 research. Nationally representative survey of 1,800+ Australian adults aged 18 years and over in February 2026. The full methodology is available on page 62 of the report.
Note: Survey findings and examples are based on Vanguard’s How Australia Retires 2026 research and reflect respondents’ opinions, expectations and intentions at the time of the survey. They should not be taken as forecasts or predictions of individual retirement outcomes.
Vanguard Super Pty Ltd (ABN 73 643 614 386 / AFS Licence 526270) (the Trustee) is the trustee of Vanguard Super (ABN 27923449966) and the issuer of Vanguard Super products. The Trustee has contracted Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) (VIA) to provide some services to members of Vanguard Super. Any general advice is provided by VIA. The Trustee and VIA are both wholly owned subsidiaries of The Vanguard Group, Inc. (collectively, “Vanguard”).
Source: Vanguard
Reproduced with permission of Vanguard Investments Australia Ltd Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance. © 2026 Vanguard Investments Australia Ltd. All rights reserved. Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.
What is a managed fund

A managed fund lets you hand investment decisions to a fund manager.

How a managed fund works


In a managed fund, money from many investors is pooled and invested to match the fund’s investment strategy. The strategies can range from lower-risk cash funds to higher-risk share and property funds. A managed fund can be a simple way to buy a mix of investments in one product.

A fund manager makes investment decisions. The company that legally operates the fund is called the responsible entity or fund operator.

When you invest in a managed fund, you don’t own the underlying investments directly. Instead, you own a stake in the fund. The value of the fund can go up or down. Some funds also pay you income, called distributions.

Some managed funds are bought and sold on an exchange like the ASX. These can include exchange-traded funds, or ETFs.

If you have super, it is likely you already invest in managed funds.

Smart Tip: Managed funds go by different names. You may see terms like unit trust, mutual fund, managed investment scheme, or Corporate Collective Investment Vehicle (CCIV).

Types of managed funds

What managed funds invest in

Single asset managed funds

These funds invest in one asset class. An asset class is a group of similar investments.

Cash funds – invest in very low-risk, short-term investments like bank deposits and short-term government bonds. They are low risk, but returns are usually lower too.

Fixed interest or bond funds – invest in loans to governments and companies. They can hold higher-risk loans that pay more interest.

Private credit funds – invest in loans that are not publicly traded. Risk and return depend on the borrowers and how the loans are structured. These can be higher risk.

Mortgage funds – invest in property loans. They can pay income so long as their borrowers keep paying. They can fall in value if borrowers default.

Property funds – invest in property or property-related assets. Some are higher risk.

Share (equity) funds – invest in shares in Australian or overseas companies. They can offer higher returns. Their value can also swing more sharply.

Alternative investment funds – include hedge funds, private equity, derivatives and commodities. These can be higher risk and more complex.

Mixed asset or multi-sector managed funds

These funds invest across more than one asset class. They are usually labelled by how much of the fund is held in growth assets like shares and property, and defensive assets like cash and bonds.

Growth – around 85% growth assets, the rest defensive.

Balanced – around 70% growth assets, the rest defensive.

Conservative – around 30% growth assets, the rest defensive.

Cash – 100% cash or cash-equivalents such as short-term deposits and bank bills.

How managed fund investments are chosen

Active funds rely on a fund manager to make ongoing decisions about investments. Some aim to beat a market index. Others aim to produce steady income or protect against loss. Some active funds use an absolute return strategy that aims for positive returns regardless of what markets are doing.

Passive funds – also called index funds – try to match a market index rather than beat it. There is less day-to-day decision-making, so fees are usually lower than active management fees.

Responsible, sustainable or ethical funds screen investments against environmental, social or governance criteria. These can be active or passive.

Benefits of managed funds

Managed funds can make investing easier for people who do not want to choose every investment themselves.

Benefits include:

  • access to a range of investments in one product

  • professional management

  • easier diversification, which means spreading your money across different investments

Risks of managed funds

Managed funds are not risk-free. The value of your investment can fall, and you may get back less than you invested.

Risks can include:

  • market risk – the assets in the fund can fall in value because of events affecting the entire market

  • sector risk – a fund focused on one part of the economy can be hit harder when that sector does badly

  • liquidity risk – you may not be able to get your money out as quickly as expected, and funds can restrict, delay or stop withdrawals in some circumstances

  • currency risk – overseas investments can be affected by changes in exchange rates

  • inflation risk – your returns may not keep up with rising prices, so your money buys less over time

  • interest rate risk – changes in interest rates can affect the value of the fund’s investments, especially bonds and other loans

  • credit risk – a borrower that the fund has lent to may not repay the loan

  • concentration risk – holding a small number of investments means any single loss has a bigger impact on the fund

  • gearing risk – if the fund borrows to invest, both gains and losses are magnified

Not every managed fund will have all these risks. The main risks depend on what the fund invests in and how it is managed.

Mia buys a diversified managed fund

Mia has saved $8,000 and wants to start investing in shares. She does not feel confident choosing individual shares, so she looks at managed funds that invest in Australian shares and overseas shares. She reads the Product Disclosure Statement to check how the fund invests, the fees she will pay, and the level of risk. Mia sees that using a managed fund could help her access a diversified mix of investments to lower her risk. She buys units directly with the manager.

Deciding if managed funds are right for you

There are a lot of different ways you can invest your money – managed funds are just one option.

Managed funds might suit you if:

  • you want a simple way to invest

  • you want your money spread across a range of investments

  • you do not want to choose and manage each investment yourself

  • you are comfortable that the value can rise and fall

Managed funds may not suit you if:

  • you want full control over every investment choice

  • you need your money back at short notice

  • you do not want to pay ongoing fees

  • you are not comfortable with the risk of losses

Managed funds are not an appropriate investment for everyone. It’s important to consider your investing timeframe and risk tolerance.

Contact us if you have any questions.

Source: Moneysmart
Reproduced with the permission of ASIC’s MoneySmart Team. This article was originally published at
https://moneysmart.gov.au/managed-funds-and-etfs/what-is-a-managed-fund
Important note: This provides general information and hasn’t taken your circumstances into account. It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person. Past performance is not a reliable guide to future returns.
Important
Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.
Learn how defined benefit super works and what it could mean for retirement. 

What is defined benefit super?

Defined benefit super is a type of super account that works differently from most other super accounts.

Most defined benefit super accounts were set up by an employer. The employer’s rules help determine what you’ll get when you retire.

Defined benefit super accounts are less common and only accept certain workers or no longer take new members.

Most super accounts have a balance that rises and falls over time, based on how much money you and your employer put in and how you invest it. This affects what you’ll get when you retire.

With a defined benefit account, your super fund uses a formula to work out what you’ll get instead.

 If you’re thinking about leaving a defined benefit fund, talk to your super fund, or speak to us first. Some funds offer benefits that you may lose if you leave, and you generally can’t rejoin.

How a defined benefit account works

The formula your fund uses to work out what you’ll get when you retire may differ from what other defined benefit funds use.

It may consider:

  • the money your employer puts in, and any contributions you make (if your fund allows them)

  • your average salary before retirement

  • how long you worked for your employer

  • your age when you retire.

For example, a retirement benefit calculation might look like this.

A fund uses the following formula to work out your benefit (i.e. how much you’ll get) at retirement:

Average salary for the last 3 years × total years of service with the employer who sponsors the defined benefit account × benefit factor.

If a member:

  • had an average salary of $100,000

  • worked for 20 years at the employer, and

  • has a benefit factor of 0.15

their estimated retirement benefit would be:

$100,000 × 20 × 0.15 = $300,000

Example only
This example is simplified to show how a defined benefit account may work. Every defined benefit fund uses its own formula. Your fund may use different factors when calculating your benefit.

Are defined benefit funds still available?

Most defined benefit funds no longer accept new members. Many were offered by government employers, public sector organisations, universities and large employers.

If you’re already a member, you can usually stay in the fund while you’re eligible.

What happens when you retire?

When you retire, your defined benefit fund may offer:

  • a regular income stream

  • a lump sum, or

  • a combination of both.

Your options depend on your fund. 

What is a defined benefit income stream?

A defined benefit income stream pays you a regular income from a defined benefit super scheme.

Your fund works out how much you receive.

Unlike an account-based pension, payments do not usually depend on an account balance or investment returns.

Payments, tax and death benefits can vary between funds.

Understand how different retirement income options can work together to fund your retirement including account-based pensions and lifetime income streams. 

Before making changes to your defined benefit super

Defined benefit accounts can offer benefits that other super accounts don’t.

Making changes may affect:

  • your future retirement income

  • your access to pension benefits

  • the tax you’ll pay

  • benefits for your partner or dependants.

Before you decide, contact your fund and consider speaking to us for financial advice.

High-pressure sales tactics are putting your super savings at risk. Be on red alert for phone calls, click bait advertising and promises of unrealistic returns to encourage you to put your super into risky investments. Stop, think carefully, and check the claims first.

Questions to ask your fund

Every defined benefit fund works differently. Your fund can explain how your account works.

You may want to ask:

  • how your benefit is calculated

  • what options you have at retirement

  • whether you can receive a pension, lump sum or both

  • how your benefit may be taxed

  • what happens if you leave the fund or transfer your benefits.

Source: Moneysmart
Reproduced with the permission of ASIC’s MoneySmart Team. This article was originally published at https://moneysmart.gov.au/how-super-works/defined-benefit-super-explained
Important note: This provides general information and hasn’t taken your circumstances into account.  It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person.  Past performance is not a reliable guide to future returns.
Important
Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.
In Australia, there are both ownership and rental opportunities to choose from when deciding on the best retirement living option for you.

Key points:

  • There are varying tenure types that can impact your rights over a property in a village

  • Make sure to understand all the costs and fees that are associated with taking a placement in a retirement village

  • Legislation and regulations differ depending on the State or Territory you live in

Generally, the deciding factor of whether you rent or buy is subject to your current financial situation.

However, you should also consider the retirement lifestyle you want to lead and whether ownership or renting will best assist in reaching those wishes and desires.

Retirement villages can be a really attractive option after you retire, encompassing a safe environment with a close-knit community of older people with similar interests and hobbies, and active social groups.

In most cases, moving into a retirement village is a great way to start downsizing your possessions and assets.

Ownership and legalities

There are different pros and cons when it comes to owning or renting a home in a retirement village.

For instance, if you rent a home, it can be less expensive depending on how long you live there. Whereas, if you buy, you don’t have to worry about any rental issues and have greater control over your home.

Either way, a retirement home will cut into your superannuation, along with additional costs and fees associated with living in a village.

Property ownership in retirement villages comes under slightly different legislation to normal homeownership.

They have different forms of legal title and occupancy rights, and other costs such as stamp duty may or may not apply.

Types of tenure

The various forms of occupation or ownership rights of retirement villages are referred to as ‘tenure’. They will include provisions for resident consultation about the management of the community and the use of the village facilities.

The legal forms of tenure for buying into retirement villages are:

Leasehold estates: The owner/developer continues to own the property, however, you pay the market value of the unit in exchange for a period of time (49 – 199 year lease). This is generally the most common form of tenure used by ‘for profit’ developers.

Licences to occupy: The village developer or owner gives you a licence to occupy your unit which means you are permitted to stay under certain conditions such as not altering the property or surrounding gardens. This form of tenure is generally the most common used by ‘not-for-profit’ developers.

Company share arrangement: The village is still owned by the retirement village developer. They will sell you shares which entitles you to live in your unit. Although some retirement villages use this tenure, it’s not a common form of tenure.

Strata title ownership: Similar to regular strata-title schemes where the property is divided into units, this operates as a direct ownership structure. You pay the agreed purchase price, are registered on the title deed and become a member of the owners’ corporation. However, unlike regular strata, the retirement village operator may have to approve you as a resident and you sign a management contract with the village owner.

This is not a common form of tenure for retirement villages.

Community title ownership: This is a very rare form of tenure for retirement villages and operates on a direct ownership structure similar to strata, except in community title, the land is divided into ‘Lots’.

Ongoing costs

Even though you have paid the market value for your property under the different tenures, you will still have ongoing costs and fees to pay in addition to your regular utility bills and in some villages, council tax.

These additional costs are sometimes known as service or maintenance fees and cover costs for the village management and maintenance.

Be across all the costs and fees that are involved with living in a village before you move in so you are not surprised by any unexpected fees.

Always read the resident’s handbook and take legal and financial advice so you fully understand what you are buying into and what your responsibilities are.

Rental units

Some residential villages do offer accommodation rental units, sometimes known as periodic tenancy, but these are generally reserved for people with limited financial resources and are usually income assessed.

Because of this, rental units are often in high demand and you may have difficulty finding one.

Where do I find a rental unit?

Rental units come in all shapes and sizes, and can be found in both small and large villages or retirement living complexes.

The main providers of rental accommodation for seniors are non-profit organisations such as religious, charitable and other benevolent organisations and local councils. However, the private sector is beginning to develop more purpose–built rental accommodation for seniors.

How much is the rent?

You will generally be charged a rental that is a percentage of the age pension plus maximum rent assistance available from Centrelink (regardless of whether you are receiving the age pension or rent assistance).

What services do rental developments offer?

Rental developments may offer the following services:

  • Self-contained units with quality fittings

  • The provision of all meals

  • Laundry services

  • Communal facilities

  • Social activities

  • Secure environment

  • Independent lifestyle

Government legislation

There is legislation to protect the rights of retirement village residents, but this is regulated by the individual States and Territories.

The legislation for each State and Territory Retirement Acts can be found by clicking on the following links:

ACT: Retirement Villages Act 2012 and Regulations

NSW: Retirement Villages Act 1999 and Regulations

NT: Retirement Villages Act 1995 and Regulations

QLD: Retirement Villages Act 1999 and Regulations

SA: Retirement Villages Act 2016 and Regulations

TAS: Retirement Villages Act 2004 and Regulations

VIC: Retirement Villages Act 1986 and Regulations

WA: Retirement Villages Act 1992 and Regulations

Some states and territories also have Resident Associations who can help with advocacy, legal aspects and also promote the rights of residents to all levels of government.

Source: Aged Care Guide
Reproduced with permission of Care & Co Media. This article was originally published on https://www.agedcareguide.com.au/information/renting-or-owning
Important: This provides general information and hasn’t taken your circumstances into account. It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person. 
Any information provided by the author detailed above is separate and external to our business. Our business does not take any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.
Floating rate bonds tend to receive less attention than shares or fixed rate bonds.

Yet in Australia, floating rate bonds are far from niche. They play a starring role in Australia’s credit market as the favoured source of debt funding by the major banks.

Floating rates are a familiar concept in our financial lives too, with most Australian mortgages structured on variable rather than fixed interest rates.

Floating rate bonds can also deliver important benefits in a diversified portfolio. By adjusting their interest payments as market rates change, they offer the potential for regular income, lower price sensitivity to interest rate movements and an additional source of diversification alongside other investments.

What are floating-rate bonds?

Like regular fixed income bonds, floating rate bonds are loans made to governments or companies that pay investors interest.

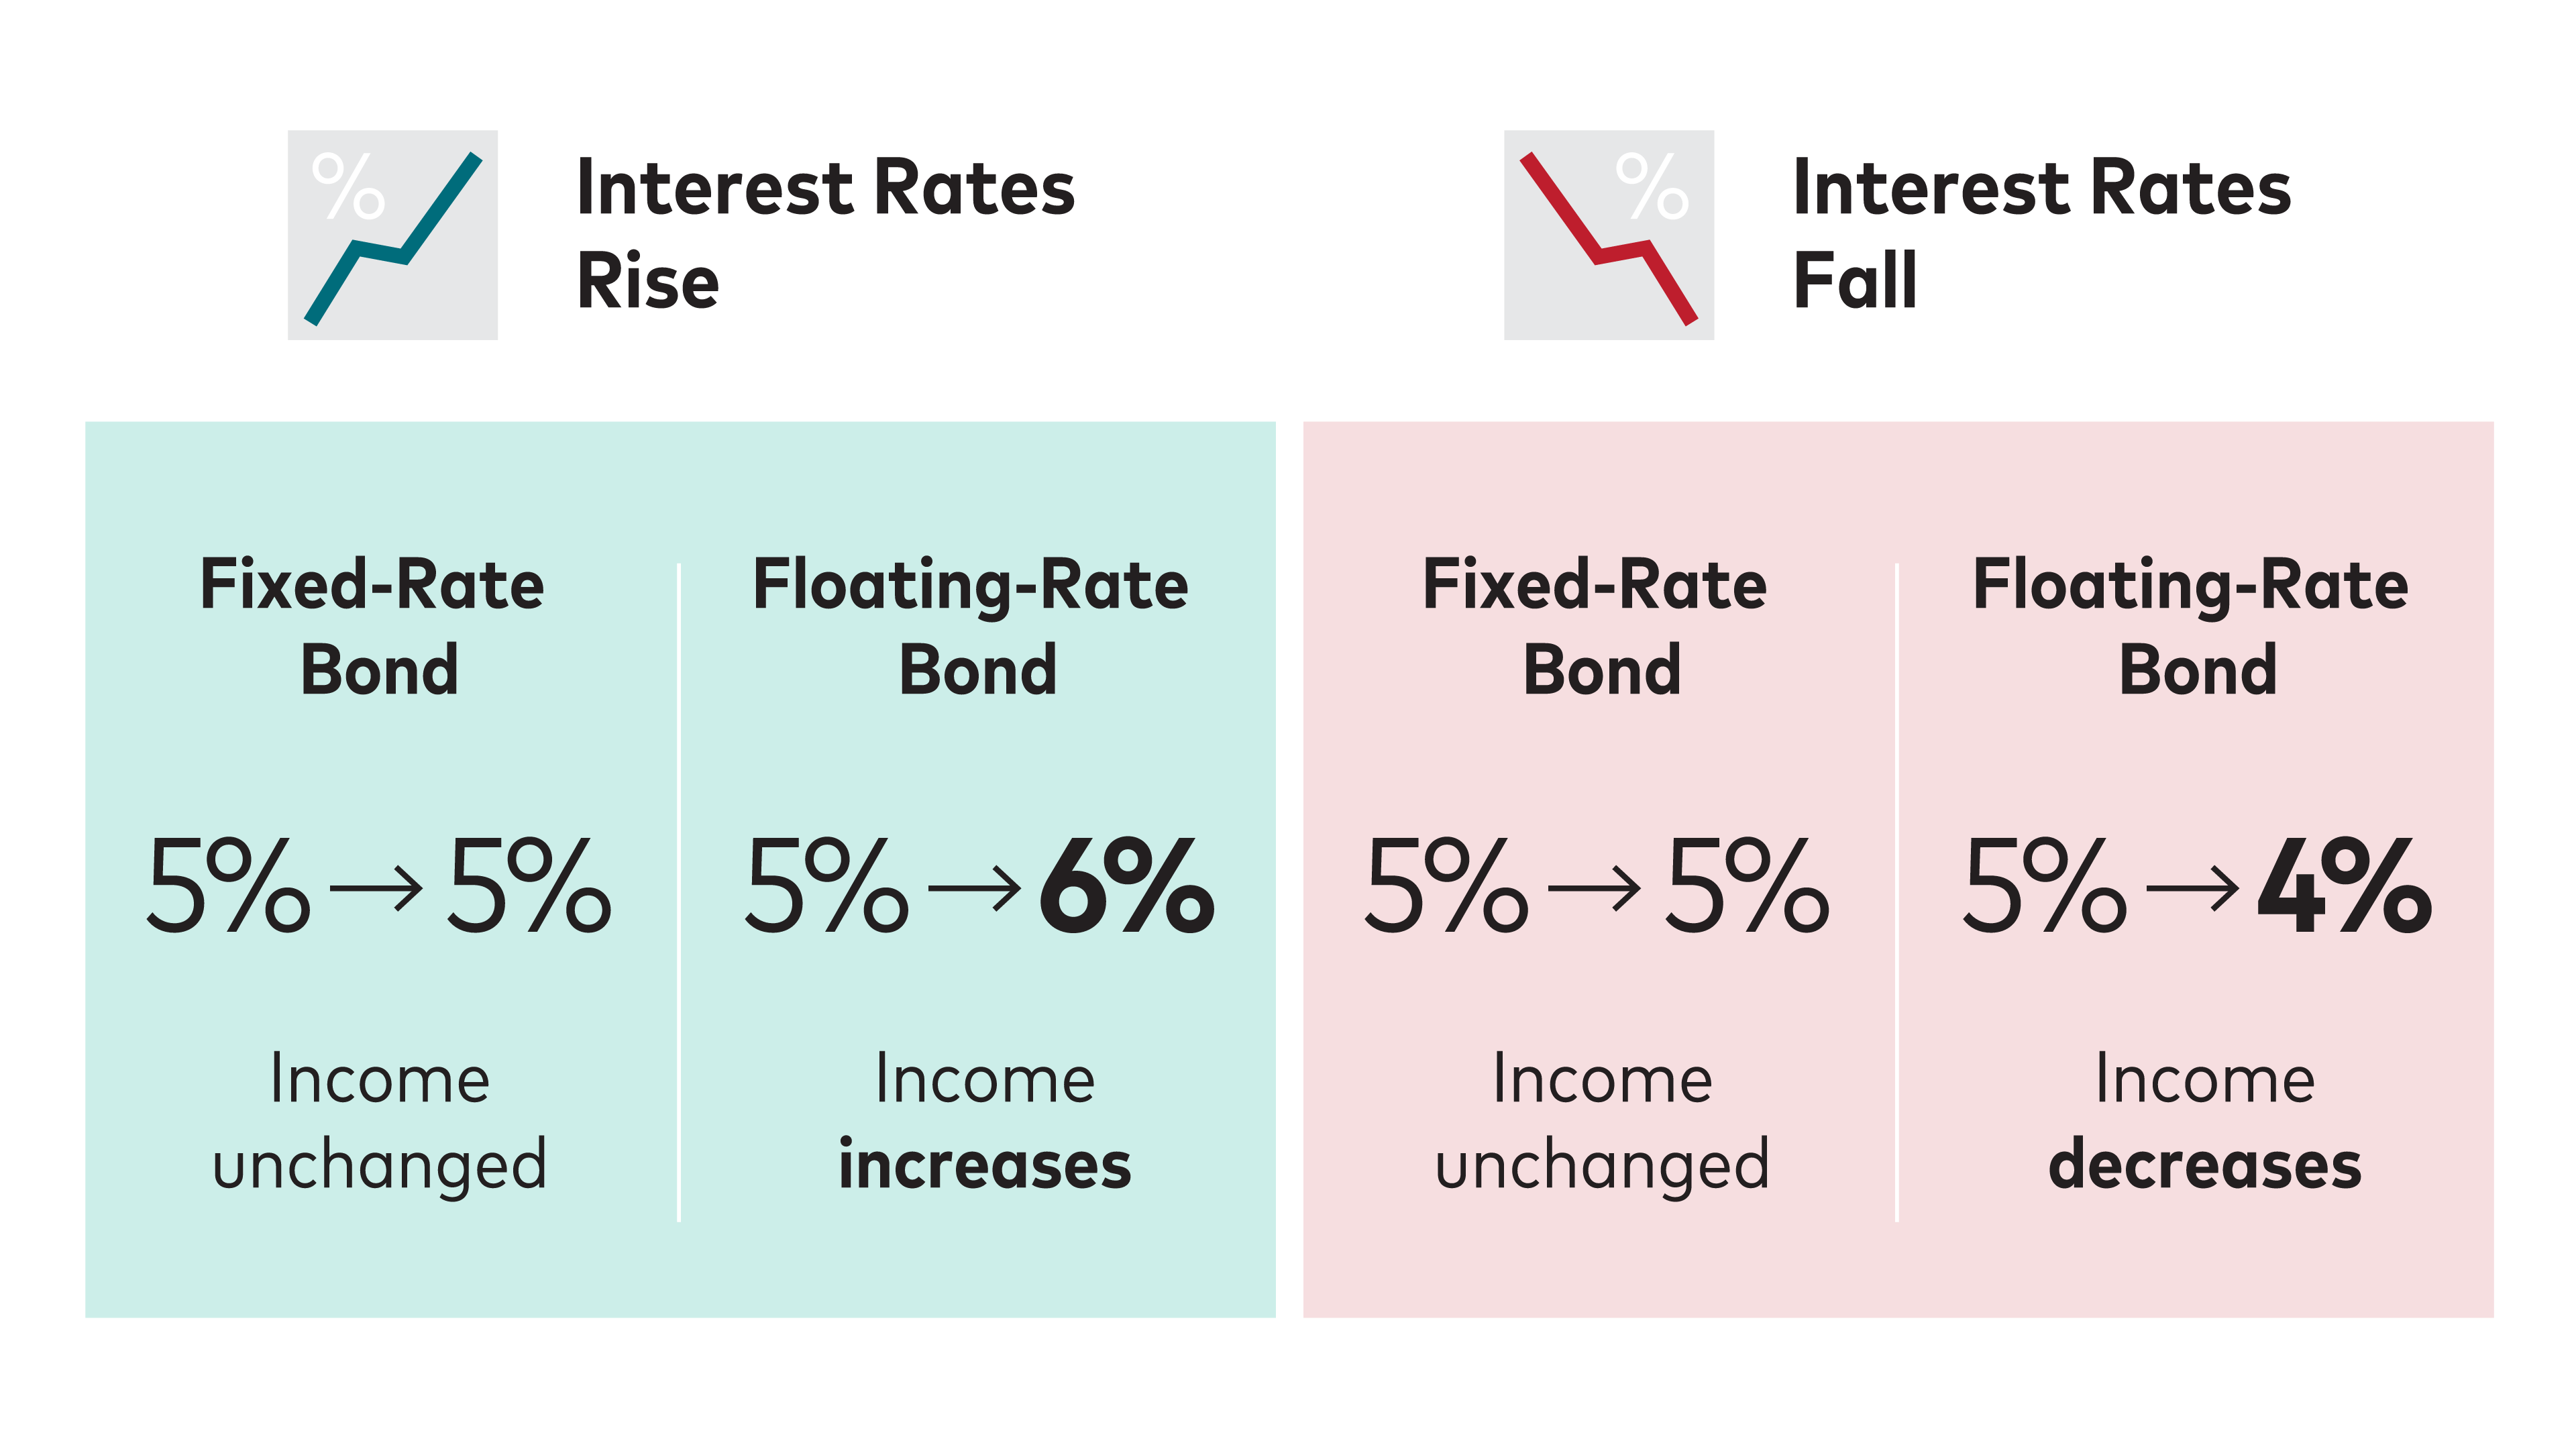
The key difference is that the interest payments on floating rate bonds can change over time. Rather than being fixed for the life of the bond, they typically move in line with short-term interest rates.

This means investors may benefit from higher income payments when interest rates rise, while still maintaining exposure to the defensive characteristics that bonds can provide.

Floating-rate bonds provide income that adjusts as interest rates change

Why investors use floating-rate bonds

Every investment plays a different role in a portfolio.

Shares can help drive long-term growth. Fixed income can help generate income and diversify risk. Cash can provide liquidity and stability. Listed property can also provide exposure to real assets and potential income, while behaving differently to shares, bonds and cash.

Floating rate bonds sit within the fixed income part of a portfolio but offer a different set of characteristics to fixed rate bonds.

1. Regular income

Many investors turn to bonds for income.

Because the interest payments on floating rate bonds adjust over time, the income generated by these securities can move with changes in market interest rates. This can make them an attractive option for investors seeking income from the defensive side of their portfolio.

2. Reduced sensitivity to interest rates

The value of fixed-rate bonds can be affected by changes in interest rates.

Floating-rate bonds are generally less sensitive to these movements because their interest payments reset periodically. As a result, their prices may experience smaller fluctuations when interest rates change.

3. Diversification

A well-diversified portfolio typically contains a mix of assets that can behave differently under different market conditions.

Floating-rate bonds can complement shares, cash and traditional bonds by providing an additional source of income and diversification.

Accessing floating rate bonds through a single investment

For many investors, building a diversified portfolio of individual bonds can be complex.

Exchange-traded funds (ETFs) provide a convenient way to access a broad range of securities through a single investment.

Where could floating-rate bonds fit in a portfolio?

There is no one-size-fits-all approach to investing, and every investor’s circumstances are different.

However, floating rate bonds may be worth considering for investors who are looking to:

  • Generate income from the defensive portion of their portfolio.

  • Diversify beyond shares and cash.

  • Reduce price sensitivity to changing interest rates.

  • Build a more balanced portfolio through exposure to different types of fixed income investments.

Importantly, floating-rate bonds are not intended to replace every other defensive investment. Instead, they can be used alongside cash, fixed rate bonds and other fixed income investments as part of a diversified portfolio.

A useful addition to the fixed income toolkit

Floating rate bonds have become an increasingly important part of many investment portfolios because they offer a unique combination of income potential, diversification and lower sensitivity to interest rate movements.

For investors looking to strengthen the defensive side of their portfolio, they may be worth a closer look.

Source: Vanguard
Reproduced with permission of Vanguard Investments Australia Ltd Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance. © 2026 Vanguard Investments Australia Ltd. All rights reserved. Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.

Retirement starts long before your last day at work

There are certain moments in life that reshape not just your finances, but the way you live.

Starting a family, moving overseas for a job, changing careers – retirement belongs in that same category in terms of its significance.

Traditionally, retirement has been viewed as a single milestone celebrated on the day you stop working. But in reality, it’s one of the longest and most significant chapters of your life – one that’s being reshaped by longer life spans, evolving retirement rules and rising living costs. 

With Australians now living longer than ever, retirement can span decades, bringing new priorities, changing spending habits and different financial decisions along the way.1

That means retirement isn’t simply something to prepare for. It’s something you’ll need to navigate through.

Know what you’re aiming for

Before thinking about how you’ll fund retirement, however, it’s worth asking a simpler question: What kind of retirement do you actually want?

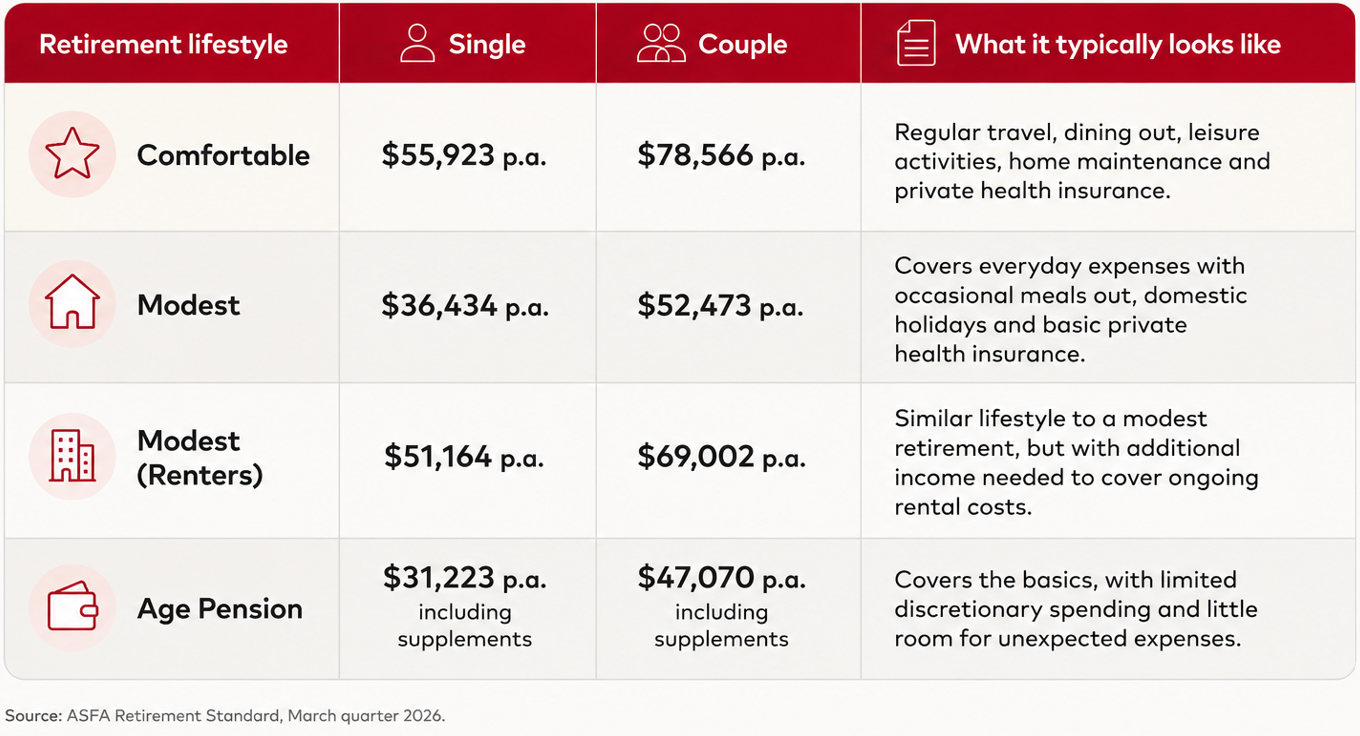
The Association of Superannuation Funds of Australia (ASFA) Retirement Standard provides a useful benchmark by estimating the annual income needed to support different retirement lifestyles.

There’s no right or wrong answer. Some Australians dream of travelling the world, while others are happiest spending more time with family, pursuing hobbies or enjoying a slower pace of life closer to home.

The important thing is having a destination in mind. After all, it’s difficult to know whether you’re saving enough – or investing appropriately – if you don’t know what you’re trying to fund.

With that in mind, here are the three broad phases of retirement and the financial considerations that tend to become most important in each.

Phase 1: Building your retirement runway

The five to ten years before retirement are a critical time for financial planning.

This is when many of the biggest financial decisions get made – when to retire, what sort of lifestyle you want, whether you’re saving enough and how to make the most of your remaining working years.

Having a clear retirement plan can make a meaningful difference. A recent report has shown Australians who understand the steps they need to take for retirement are significantly more confident about funding their desired lifestyle and more optimistic about their future than those without a plan.

It’s also the time to take stock of your financial position.

While seven-figure super balances often grab headlines, they’re far from the norm. Australians aged 60 to 64 have a median super balance of around $236,126 for men and $174,655 for women.2 

With many Australians approaching retirement with relatively modest super balances, making the most of available opportunities to contribute to super and strengthen retirement savings can be particularly valuable.

Here are several key questions to ask in the decade leading up to retirement: 

  • How much do I currently have in super and other investments, and will it support the lifestyle I want in retirement?

  • Are there any big-ticket experiences I want to budget for, such as a luxury cruise, overseas travel or helping my children financially?

  • Will I be in a position to pay off my mortgage before retirement?

  • Do I want to stop working completely, or gradually transition through part-time or consulting work?

  • Would downsizing or relocating improve my retirement lifestyle or financial position?

Phase 2: Putting your nest egg to work

Once retirement begins, your financial mindset will likely shift.

Instead of building wealth, the priority becomes generating an income that can support your lifestyle while ensuring your savings last for what could be another 20 or 30 years.

For many people, this can be an uncomfortable transition. After spending decades trying to grow your retirement savings, you’re now relying on them to fund your lifestyle 

Retirees also need to consider sequencing risk – the impact a market downturn can have if it occurs early in retirement while you’re simultaneously drawing an income from your portfolio.

As a result, some retirees choose to maintain exposure to growth assets alongside defensive investments and cash, depending on their circumstances, objectives and tolerance for risk.

While liquidity can help fund day-to-day spending and reduce the need to sell investments during volatile markets, growth remains important because inflation continues long after your working life ends.

Your retirement income may also come from multiple sources including investments held outside super and, depending on your circumstances, the Age Pension.

Here are several key questions to consider as you approach and enter retirement:

  1. Where will my retirement income come from – super, investments, rental income, the Age Pension or a combination of these?

  2. Is my investment portfolio still appropriate now that my focus has shifted from building wealth to drawing an income?

  3. Can my income keep pace with inflation?

  4. Do I have enough cash or liquidity to cover unexpected expenses or periods of market volatility?

  5. Am I reviewing my spending regularly to ensure my savings remain sustainable over the long term?

Phase 3: Planning your legacy

As retirement progresses, financial planning often becomes about much more than investment returns.

Many retirees begin thinking more carefully about how they’ll be cared for if their health changes, whether their current home still suits their needs and how they want their assets distributed to loved ones.

While these conversations aren’t always easy, planning ahead can provide greater flexibility, reduce stress for your family and ensure your wishes are understood well before important decisions need to be made.

At some stage during retirement, these are some of the conversations worth having:

  1. Is my will up to date, and have I reviewed my beneficiary nominations?

  2. Have I considered how I would fund aged care or additional healthcare needs if they arise?

  3. Does my current home still suit my needs, or would another living arrangement be more appropriate?

  4. Have I appointed the right people to make financial or medical decisions if I’m unable to do so?

  5. Does my estate plan reflect the legacy I want to leave for my family and loved ones?

Strategies to consider

Your retirement plan doesn’t need to be perfect. The important thing is to start early, review it regularly and adapt it as your circumstances change. 

Here are some practical strategies to consider. As always, it’s important to consider whether any strategy is appropriate for your personal circumstances and seek professional advice if needed.

  • Start small. Retirement planning doesn’t have to happen all at once. Start by discussing a few key questions with your partner (or you can contact us) such as when you’d like to retire and how much super you may need.

  • Review your super regularly. Make a habit of logging into your super account and checking your balance, investment options, fund performance and insurance cover.

  • Make the most of super contributions. If you’re still working, additional concessional (before-tax) contributions could help grow your retirement savings. 

  • Understand carry-forward contribution caps. If your total super balance is below $500,000 and you meet the eligibility requirements, you may be able to use unused concessional contribution caps from the previous five financial years.

  • Learn about downsizer contributions. If you’re 55 or over and meet the eligibility requirements, selling your home may allow you to contribute up to $300,000 each (or $600,000 per couple) into super.

Contact us if you have any questions.

1. ASFA Retirement Standard Budgets for various households and living standards for those aged 65-84 (March quarter 2026)
2. Median super balance, by age and sex, 2023–24 financial year – Australian Taxation Office

Source: Vanguard
Reproduced with permission of Vanguard Investments Australia Ltd
Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance.
© 2026 Vanguard Investments Australia Ltd. All rights reserved.
Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.